
At a certain level of wealth, even high-net-worth insurance products start showing their limitations. The coverage caps are too low, the underwriting models don’t account for the complexity of your assets, and the service model assumes a level of simplicity that doesn’t reflect your actual life. Think of it like outgrowing a tailored suit: the standard high-net-worth version fits better than off-the-rack, but once your situation changes enough, it still pulls at the seams.
Ultra high-net-worth insurance exists because the gap between standard high-net-worth coverage and the real-world exposure of individuals with $5 million, $30 million, or $100 million+ in assets is enormous. The policies are different, the limits are different, and the carriers who write these programs operate in a fundamentally different segment of the market.
Key Takeaways:
-
UHNW insurance protects homes, luxury assets, and global liability under one tailored program designed for individuals with $5 million or more in assets.
-
Coverage includes fine art, luxury vehicles, multiple properties, and worldwide risk exposure, all coordinated to eliminate gaps between policies.
-
Policies offer high limits ($5M to $100M+) and concierge-level risk management services that go well beyond reactive claims response.
-
Best suited for individuals with complex, high-value asset portfolios that standard and even high-net-worth policies can’t adequately protect.
Get a tailored ultra-high-net-worth insurance quote and protect your global assets with a custom policy. Request a personalized quote or call us directly at (239) 354-4053.
What Is Ultra High-Net-Worth Insurance?
Ultra high-net-worth insurance is a category of personal insurance designed for individuals and families whose asset profiles exceed the capacity of standard high-net-worth products. While definitions vary by carrier, most UHNW programs target individuals with a net worth of $5 million to $30 million or more.
The distinction between HNW and UHNW isn’t just about dollar thresholds. It reflects a difference in complexity. UHNW individuals typically own multiple properties across states or countries, maintain collections of fine art or vehicles, employ domestic staff, and carry liability exposure that extends into eight figures.
UHNW programs are built from the ground up for these portfolios. Coverage limits extend to $100 million or more, underwriting is individualized rather than model-driven, and the service model includes proactive risk management, dedicated advisors, and concierge-level claims handling.
If standard insurance is like buying a house from a catalog, and high-net-worth insurance is like working with an architect, UHNW insurance is like hiring a firm that designs, builds, and maintains the property for you on an ongoing basis. Every element is custom, every detail is monitored, and the relationship doesn’t end when the policy is signed.
What Does Ultra High-Net-Worth Insurance Actually Cover?
Ultra high-net-worth insurance is designed to protect a broader and more complex risk profile than a standard personal insurance package. Instead of treating each exposure in isolation, it is structured to address high-value homes, luxury assets, collections, domestic staff, personal liability, and other layered risks that come with substantial wealth and a more visible ownership profile.
High-Value Homes and Global Real Estate
UHNW property coverage addresses primary residences, secondary homes, vacation properties, and investment properties across multiple locations, including international real estate. Policies provide guaranteed replacement cost, meaning the insurer covers whatever it actually costs to rebuild to original specifications, even if construction costs have increased since the policy was written.
For properties in high-risk locations (coastal, wildfire-prone, earthquake zones), UHNW carriers provide coverage that standard markets often decline or severely restrict. Vacancy provisions for seasonal properties, coverage for staff quarters and guest houses, and protection for elaborate landscaping are typically included as standard.
Explore our personal insurance solutions to see how we structure property coverage for multi-home portfolios.
Luxury Vehicles and Specialty Assets
UHNW auto coverage uses agreed value across the board, eliminating depreciation disputes for exotic, luxury, and collectible vehicles. Policies cover multiple vehicles under a single program and extend worldwide protection for cars stored at different properties.
For yacht and aviation assets, UHNW programs coordinate marine and aviation coverage with the broader portfolio. While these policies are often underwritten separately, the carrier or broker ensures liability limits align across all asset categories so no gaps exist between marine, aviation, auto, and umbrella coverage.
Art, Jewelry, and Collectibles
UHNW collectibles coverage goes beyond standard scheduled-item policies. There are no sub-limits per item, coverage applies worldwide (including during transit, exhibition, and storage), and most programs include automatic coverage for new acquisitions up to a specified threshold.
Coverage extends to fine art, jewelry, watches, antiques, wine collections, and rare books. The underwriting process is designed to accommodate large, complex collections without excessive administrative burden.
High-Limit Personal Liability Protection
Umbrella liability is a core component of every UHNW program, with limits typically ranging from $5 million to $100 million or more. This coverage sits on top of all underlying policies and provides a unified liability shield across your entire risk profile.
For UHNW individuals, liability exposure goes well beyond standard accident and injury scenarios. It includes lawsuits from domestic staff, claims arising from social events, allegations of defamation, and liability associated with board service or charitable activities.
Global and Travel-Related Coverage
International protection is standard in UHNW programs, not an add-on. Liability coverage applies worldwide, personal property coverage extends to belongings at international residences and during travel, and emergency medical evacuation and repatriation services are included.
Optional coverages in this category include kidnap and ransom (K&R) insurance, identity theft and cyber coverage, and crisis response services, all of which address risks that are elevated for individuals with public profiles and significant financial accounts.
Risk Management and Concierge Services
One of the defining features of UHNW insurance is proactive risk management. Think of it less like traditional insurance and more like having a private risk consultant on retainer. Rather than simply responding to claims, UHNW carriers assign private risk advisors who conduct home inspections, evaluate security systems, and recommend preventative measures.
These services can include professional security assessments, water leak detection recommendations, wildfire defensible space evaluations, and reviews of contractor work. For many UHNW clients, the risk management services are as valuable as the coverage itself.
Lifestyle and Emerging Risks
The risk landscape for UHNW individuals continues to evolve. Cyber liability addresses exposure from data breaches and digital footprint risks. Event liability covers hosting large gatherings where guest injuries could generate claims. Reputation protection, while still an emerging category, addresses the costs of managing reputational damage from media coverage or public allegations.
How UHNW Insurance Is Different from Standard Insurance
UHNW insurance differs from standard insurance because it is built around customization, higher limits, broader definitions of covered property, and a more proactive approach to risk management. The goal is not just to insure more expensive assets, but to create a program that reflects the way affluent households actually live, own property, travel, entertain, and manage liability.
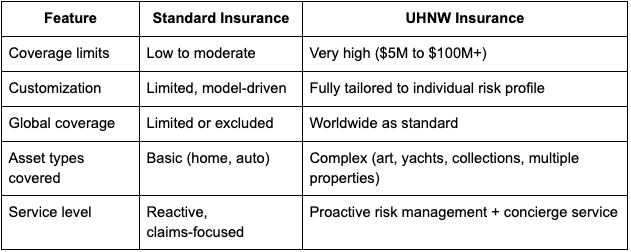
The practical impact shows up most during a claim. Standard policyholders navigate phone trees and negotiate settlements against depreciation schedules. UHNW policyholders have dedicated contacts who mobilize immediately, coordinate across multiple coverage types, and resolve claims based on actual replacement or agreed value.
What Assets Can Be Included in One UHNW Policy
UHNW programs are designed to consolidate coverage across virtually all personal asset categories: multiple homes, luxury and collectible vehicles, fine art and collections, umbrella liability, watercraft, aviation assets, personal cyber coverage, and domestic staff liability.
The consolidation isn’t just about convenience. When all coverage is coordinated under one program, liability limits align properly, coverage gaps are eliminated, and the claims process becomes significantly more efficient when a loss involves multiple coverage types simultaneously.
Not sure if your current coverage handles the full scope of your assets? Visit our Service Center for a comprehensive policy review.
Best Ultra High-Net-Worth Insurance Providers
Choosing an ultra high-net-worth insurance provider involves more than comparing brand recognition or headline premiums. The better carriers distinguish themselves through broader coverage design, claims handling, risk advisory services, and their ability to insure complex assets and liability exposures under a coordinated personal program.
Chubb Private Client is the largest and most established UHNW carrier, known for guaranteed replacement cost coverage, agreed value across all asset types, and a claims operation that consistently ranks at the top of the industry.
AIG Private Client Group offers strong global capabilities, making it particularly well-suited for individuals with international assets and travel exposure. AIG’s programs accommodate complex multinational portfolios with high-limit umbrella coverage.
PURE Insurance is a member-owned carrier focused exclusively on high-net-worth and UHNW families, known for transparent pricing and proactive risk management.
Vault Insurance has positioned itself as a modern alternative, offering flexible policy structures and a tech-forward approach to underwriting and service.
Cincinnati Private Client provides a strong option for UHNW clients, particularly those in the Midwest and Southeast, with competitive pricing and solid claims support.
Each carrier has different strengths, and the best fit depends on your specific asset profile, geographic exposure, and service priorities. Most UHNW individuals access these carriers through specialist brokers who compare options and negotiate terms across providers.
How to Choose the Right UHNW Insurance Policy
Selecting a UHNW policy starts with understanding your own risk profile in detail. Here are a few factors you can use as a starting point:
Asset Complexity
How many properties do you own, and where? Do you have collections, vehicles, or watercraft that require specialized coverage? The more complex your assets, the more important it is to work with a carrier that underwrites individually rather than applying standardized models.
Global Exposure
If you own property internationally or travel frequently, you need a program with genuine worldwide coverage, not a domestic policy with a vague international endorsement.
Liability Needs
Your umbrella limit should reflect your total asset exposure, including future earnings, not just current net worth. Plaintiffs’ attorneys calculate potential recovery based on everything you have and everything you’re likely to earn.
Service Expectations
UHNW insurance is a service-intensive product. If you expect a dedicated advisor, proactive risk management, and priority claims handling, verify that the carrier and broker deliver these rather than just marketing them.
Broker Specialization
The broker’s expertise matters as much as the carrier’s products. A broker who specializes in UHNW insurance understands the nuances of policy language, can negotiate terms that generalist brokers don’t know to ask for, and manages the ongoing relationship between your evolving risk profile and your coverage program.
Explore our insurance solutions to see how Harbour structures UHNW programs across multiple carriers.
How Much Does Ultra High-Net-Worth Insurance Cost
UHNW insurance pricing is highly individualized, and broad averages aren’t particularly useful because the range is so wide. The main variables are total insured asset value, property locations, liability limits selected, specialty asset types, and claims history.
A program covering a $3 million primary residence, a $2 million vacation home, several luxury vehicles, and a $10 million umbrella will cost significantly less than a program covering five international properties, a superyacht, an aviation asset, and a $50 million umbrella. Premiums for comprehensive UHNW programs typically start in the mid-five-figure range and can extend well into six figures annually for the most complex portfolios.
The cost reflects both the coverage and the service model. Risk management consultations, dedicated advisors, and priority claims handling are built into the premium rather than charged separately, which means comparing UHNW premiums against standard policy costs isn’t an apples-to-apples exercise.
The most reliable way to assess cost is to request proposals from multiple carriers based on your actual asset profile. Request a personalized quote from Harbour Insurance to get started.
When Do You Need Ultra High-Net-Worth Insurance
Ultra high-net-worth insurance becomes necessary when standard personal lines coverage no longer matches the value, complexity, or liability exposure of what you own. Once homes, collections, multiple residences, domestic staff, or high-profile lifestyle risks start to outgrow ordinary policy limits and assumptions, a more specialized insurance structure is usually the safer fit.
Consider UHNW insurance if any of the following apply:
You Own Multiple Properties
Owning homes in different states or countries creates coverage complexity that standard policies handle poorly. Each property has different risks, different local regulations, and different rebuilding costs, and coordinating them under one program prevents the gaps that inevitably form when they’re insured independently.
Your Net Worth Exceeds $5 Million
At this level, your liability exposure significantly exceeds what standard umbrella policies provide, and your property values likely exceed standard coverage caps. The difference between what you own and what your policies protect represents personal exposure that grows with every asset you add.
You Have Public Visibility or Legal Exposure
Business leaders, executives, board members, and public figures face an elevated risk of lawsuits, reputational claims, and targeted criminal activity. UHNW coverage addresses these exposures specifically rather than leaving them to policies that were never designed for high-profile individuals.
You Have an International Lifestyle
Frequent international travel, foreign property ownership, or global business activities require insurance that operates seamlessly across borders. Domestic policies with vague international endorsements don’t provide the same protection as programs built for global exposure from the ground up.
Building a UHNW Program That Fits Your Life with Harbour Insurance
The right UHNW program isn’t one-size-fits-all. It’s built around your specific assets, your travel patterns, your liability exposure, and the level of service you expect. Working with a specialist broker who understands both the carriers and the coordination challenges ensures your program reflects your actual risk rather than an underwriting model’s best guess.
Harbour Insurance has helped high-net-worth individuals and families structure comprehensive insurance programs for over a decade. Learn about our agency and how we coordinate coverage across multiple top-tier carriers.
Have questions about whether your current coverage matches your actual exposure? Contact our team or call us at (239) 354-4053 to speak with a specialist.
Frequently Asked Questions
What is the minimum net worth for UHNW insurance?
Most UHNW carriers set entry thresholds at approximately $5 million in net worth, though some programs start lower and others are designed for $10 million or $30 million+. The threshold reflects asset complexity as much as dollar amount.
Is worldwide coverage included?
Yes. Genuine UHNW programs provide global protection as a standard feature, covering liability, personal property, and emergency services wherever you are.
Does UHNW insurance include umbrella liability?
Yes. High-limit umbrella coverage is a core component, typically ranging from $5 million to $100 million or more, sitting on top of all underlying policies.
Can I bundle all assets under one policy?
UHNW insurance is designed for consolidation. While certain specialty coverages (aircraft, superyachts) may require separate policies, they’re coordinated under a single program managed by one broker to ensure no gaps.
Harbour Insurance Agency is an independent insurance agency helping ultra-high-net-worth individuals and families structure comprehensive, globally coordinated coverage programs. Our agents work with multiple top-tier carriers to build tailored protection across property, liability, collections, and specialty assets.




