
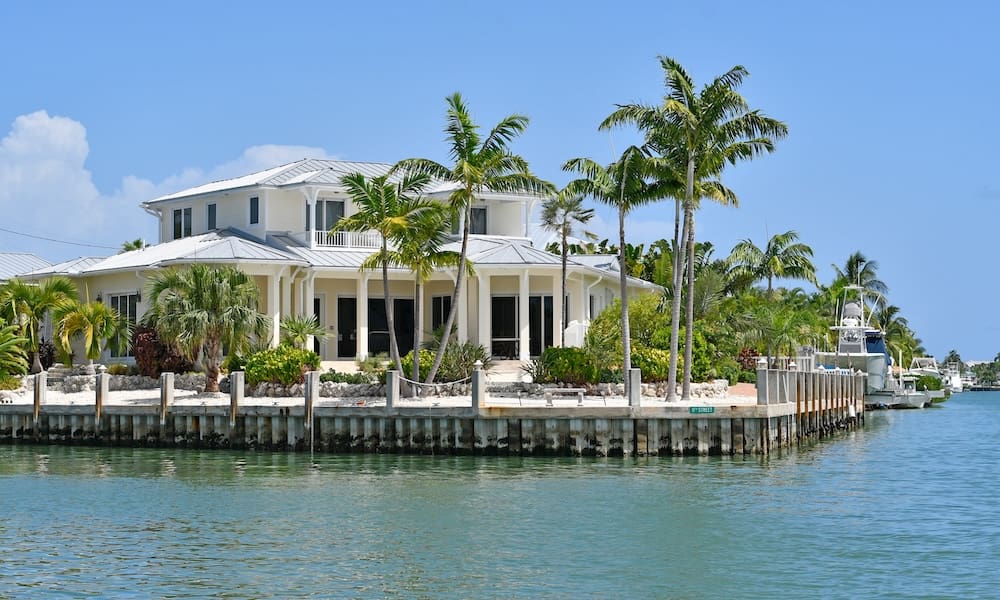
Florida home insurance is among the most expensive in the country, and for high-value properties the numbers climb fast. A $1 million home typically runs $6,000 to $12,000 per year. A $5 million coastal estate can exceed $25,000 annually before flood coverage is added.
Hurricane risk, coastal exposure, limited carrier availability, and luxury rebuilding costs all push premiums above what owners of comparable properties in other states pay. Specialized coverage with appropriate limits isn’t optional at this level. It’s the only structure that actually reflects what you own.
Get pricing for your Florida property. Compare high value home insurance options | Request a Florida luxury home insurance quote | Speak with a high net worth insurance advisor
Florida is not a normal homeowners insurance market, and high-value properties sit at the sharp end of that reality. The combination of hurricane exposure, coastal flood risk, a thinning carrier market, and the cost of rebuilding luxury construction means that how much home insurance is in Florida is a question with a very different answer than it would be in Colorado or Tennessee.
Standard policy structures don’t fit high-value Florida properties well. The limits are too low, the valuation methods too conservative, and the coverage for wind and flood too fragmented to protect what a $2 million or $5 million property actually represents. Understanding the pricing landscape is the first step toward building coverage that holds up when a storm comes ashore.
How Much Is Home Insurance in Florida on Average?
For high-value properties, Florida premiums scale sharply with home value and location. The ranges below reflect typical annual premiums for well-maintained properties with updated roofs and standard deductible structures. Coastal location, older construction, and higher deductible selections will push numbers toward the upper end or beyond.
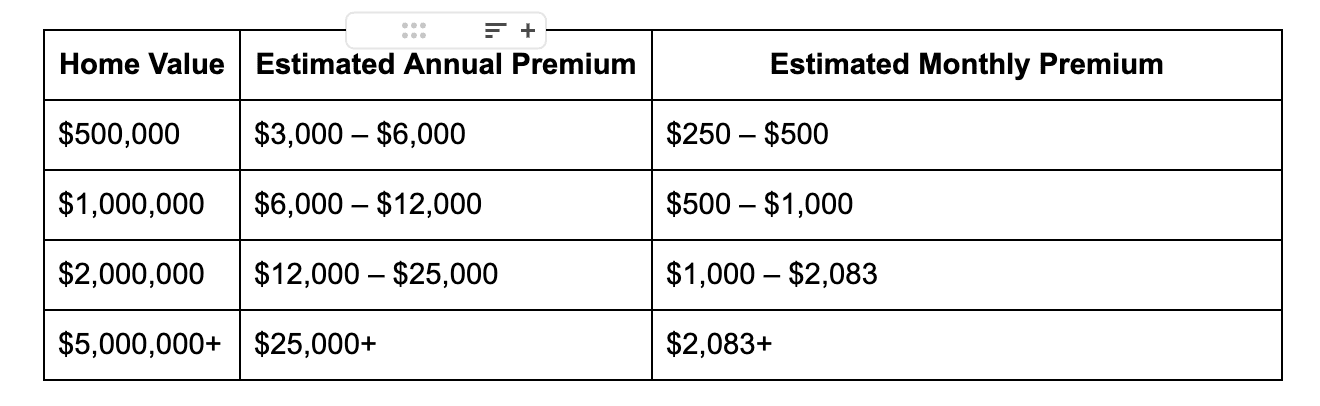
These ranges reflect general market conditions and are not quotes. Individual premiums vary significantly based on location, construction, roof age, flood zone, and carrier.
How Much Is Home Insurance in Florida Per Month?
Monthly premiums break down roughly as follows across property tiers:
-
Mid-range homes ($400K–$700K): $250–$500 per month
-
High-value homes ($1M–$2M): $500–$1,500 per month
-
Luxury coastal properties ($2M+): $2,000+ per month, before separate flood coverage
For coastal estates and waterfront properties, flood insurance adds a separate and often substantial cost on top of the base homeowners’ premium. See Harbour’s flood insurance options for a clearer picture of what combined coverage looks like for coastal properties.
Why Florida Home Insurance Is So Expensive
Florida’s insurance market is structurally different from the rest of the country. The pricing isn’t arbitrary. It reflects a genuine concentration of catastrophic risk that has caused multiple insurers to exit the state entirely over the past decade, leaving a thinner carrier market that prices the remaining risk more aggressively.
Hurricane Risk
Florida sits in the path of Atlantic hurricane activity more consistently than any other state. The cumulative claims exposure from major storm events has fundamentally shaped how carriers price residential risk across the entire state, not just in coastal counties. Even inland properties carry elevated wind risk during major storm events, and that exposure is priced into every policy.
Coastal Exposure
Coastal properties face compounded risk: wind damage from hurricane-force conditions, storm surge flooding that standard homeowners policies don’t cover, saltwater corrosion that accelerates structural wear, and the sheer rebuilding cost of waterfront locations where access, materials, and labor all carry premiums. A waterfront estate that sustains major storm damage is among the most expensive residential losses a carrier can face, and premiums reflect that reality.
Rebuilding Costs
High-value Florida homes frequently feature custom construction, premium finishes, impact-resistant materials, and architectural details that drive replacement cost well above standard residential benchmarks. A $3 million home with custom stone floors, high-end millwork, and a chef’s kitchen doesn’t rebuild at the same cost per square foot as a standard residential structure, and carriers that specialize in high-net-worth properties underwrite that distinction.
Insurance Market Conditions
Florida’s carrier market has contracted significantly. Multiple insurers have reduced their Florida exposure or exited entirely, leaving the market concentrated among a smaller group of carriers. That concentration removes competitive pricing pressure and gives the remaining carriers more latitude on rate. For high-value properties, the specialist private client carriers, Chubb, AIG Private Client, PURE, and others, represent the most stable long-term options because they’ve maintained their Florida presence more consistently than standard carriers.
High Value Home Insurance Cost by Property Type
Location and property type interact significantly with base home value to determine final premium. Two $2 million homes, one inland and one on the water, can carry meaningfully different premiums even with identical construction quality and coverage structures.
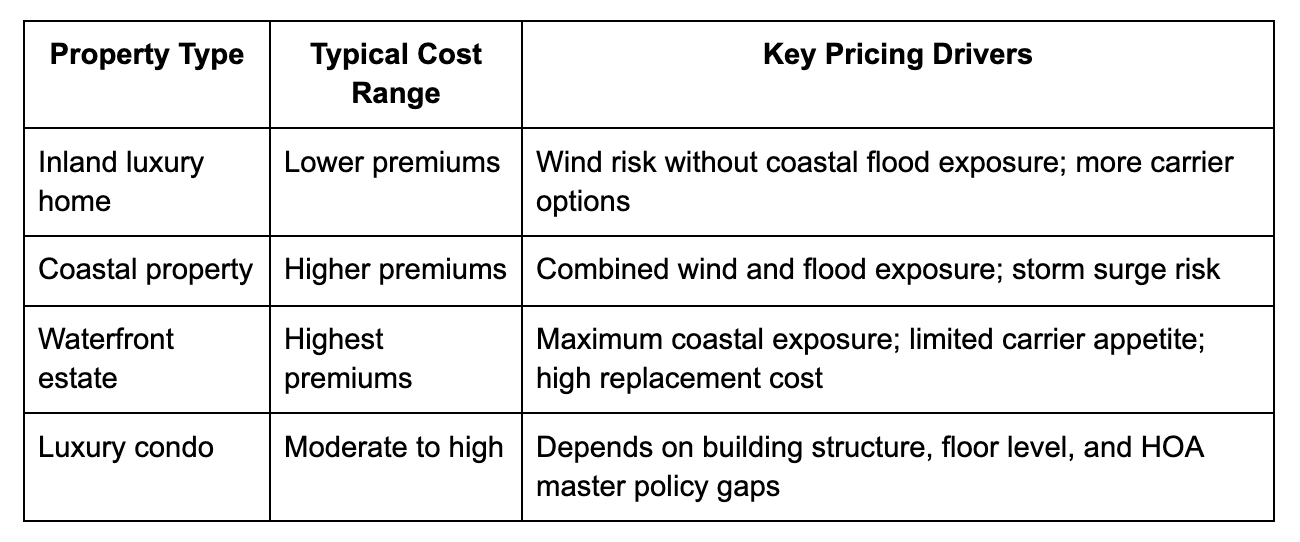
For luxury condo owners, the interaction between the HOA master policy and individual unit coverage creates specific gaps that are worth reviewing carefully. The master policy typically covers building structure but not interior finishes, personal property, or liability, leaving the individual unit policy to fill those gaps at values that reflect actual cost rather than builder-grade replacements. Contact Harbour to review condo coverage gaps for high-value units.
Compare coverage options for your specific property type. Compare high value Florida home insurance | Request a coastal property insurance quote
What Affects High-Value Home Insurance in Florida?
The variables that drive premium for high-value Florida properties are more numerous and more impactful than most owners expect. Each one is worth understanding before you request quotes, because they directly affect what carriers will write and at what price.
-
Location is the single largest variable. Coastal counties, particularly Miami-Dade, Broward, Palm Beach, Collier, and Monroe, carry significantly higher premiums than inland locations. Distance from the coast, flood zone designation, and proximity to water all factor into the calculation.
-
Home value and replacement cost set the ceiling for the dwelling coverage limit, which is the basis for your premium calculation. For custom-built luxury properties, replacement cost can significantly exceed market value, and underinsuring to reduce premium creates a dangerous gap.
-
Construction type matters because impact-resistant construction, reinforced rooflines, and hurricane-rated windows and doors reduce wind exposure. Older construction built before modern Florida building codes may carry higher premiums and face stricter underwriting scrutiny.
-
Roof age is one of the most heavily weighted factors in Florida home insurance underwriting. Carriers increasingly require roofs to be under 15 years old for standard underwriting, and roofs approaching that threshold can trigger surcharges, non-renewal, or coverage limitations. A roof replacement before renewal can produce meaningful premium savings.
-
Hurricane mitigation features, including storm shutters, impact windows, reinforced garage doors, and roof-to-wall connections, reduce wind exposure and can qualify for Florida’s wind mitigation credits, which directly reduce the windstorm portion of your premium.
-
Flood zone determines whether flood insurance is required by a lender and how expensive it is to obtain. Properties in FEMA-designated high-risk zones (Zone AE, VE) face higher flood insurance costs than those in moderate or low-risk zones.
-
Deductible selection has a direct and meaningful impact on premium. Hurricane deductibles in Florida are percentage-based rather than fixed-dollar, typically 2% to 5% of insured value. On a $2 million home, a 2% hurricane deductible means $40,000 out of pocket before coverage kicks in. Understanding the tradeoff between premium savings and out-of-pocket exposure is essential before selecting a deductible structure.
Does Location in Florida Affect Insurance Cost?
Significantly. Coastal counties in Southeast and Southwest Florida consistently carry the highest premiums in the state. Moving from a waterfront property to a comparable home a few miles inland can reduce premium by 20% to 40% on equivalent coverage, purely based on reduced coastal exposure.
Hurricane and Flood Coverage Costs
For high-value Florida properties, hurricane and flood coverage deserve their own analysis because they operate differently from standard homeowners coverage and carry costs that compound the base premium significantly.
How Much Is Hurricane Insurance in Florida?
Hurricane coverage is typically included in a standard Florida homeowners policy rather than sold separately, but it carries its own percentage-based deductible that applies specifically to hurricane-caused losses. That deductible is typically 2% to 5% of the insured dwelling value, meaning the out-of-pocket exposure before coverage activates can be substantial on high-value properties.
On a $3 million home with a 2% hurricane deductible, the first $60,000 of hurricane damage comes out of pocket. On a 5% deductible, that number rises to $150,000. Selecting a hurricane deductible without understanding its dollar equivalent on your specific insured value is one of the most common and expensive coverage mistakes Florida homeowners make.
Does Florida Require Flood Insurance?
Florida does not universally require flood insurance, but lenders require it for properties in FEMA-designated high-risk flood zones, and for coastal properties it’s rarely optional in any practical sense. Flood insurance is a separate policy from homeowners coverage, typically written through the National Flood Insurance Program (NFIP) or private flood carriers.
For high-value properties, the NFIP’s maximum building coverage of $250,000 is almost certainly insufficient. Private flood insurance provides higher limits and broader coverage terms for luxury properties, and for many high-value Florida homeowners it’s the more appropriate structure. See Harbour’s flood insurance resources for Florida for a deeper breakdown of requirements by zone and lender type.
Florida Home Insurance Cost by Deductible
Deductible selection is one of the most direct levers available for managing Florida home insurance premiums, but the tradeoffs need to be understood clearly before making a choice.
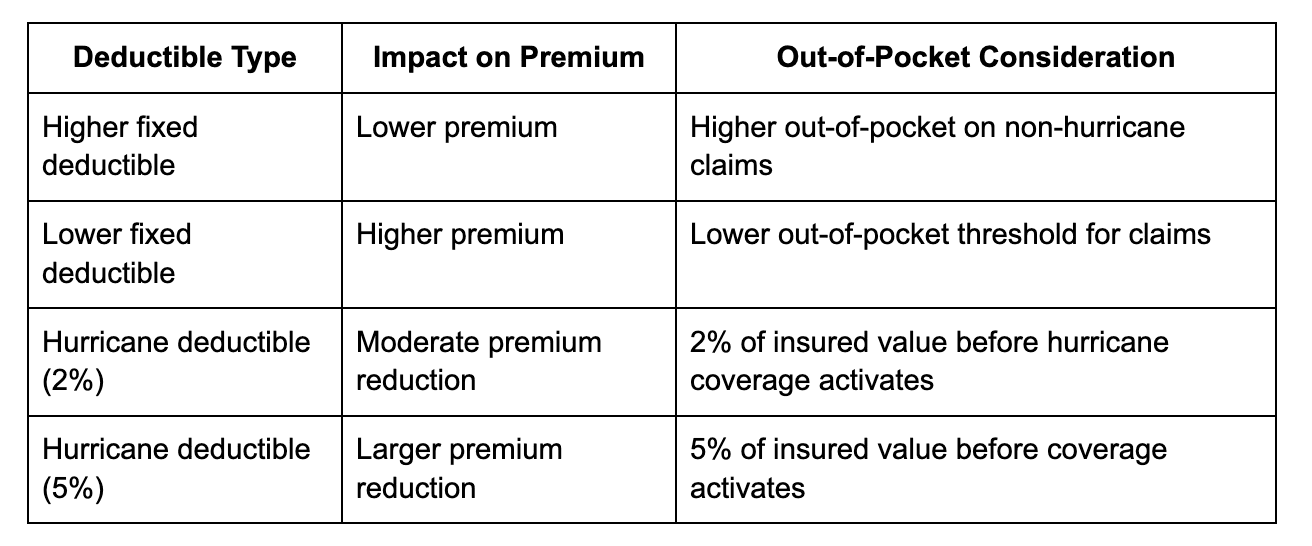
For a $2 million home, the difference between a 2% and 5% hurricane deductible is $60,000 in out-of-pocket exposure. The premium savings from selecting the higher deductible rarely justify that gap for most high-net-worth homeowners, but the right answer depends on your specific financial situation and risk tolerance.
How Florida Insurance Rates Are Calculated
Carriers underwriting high-value Florida properties evaluate a combination of property-specific and market-level factors to arrive at a premium. Understanding the calculation helps explain why two similar homes carry different premiums and where opportunities to reduce cost exist.
The primary rating factors are replacement cost of the dwelling (not market value), construction materials and quality, hurricane and wind exposure based on location and construction features, flood zone designation, claims history on the property and by the insured, roof age and condition, presence of hurricane mitigation features, and the overall coverage structure including limits and deductible selections.
For high-value properties, carriers also evaluate the quality of finishes and custom features that affect rebuilding cost. A home with imported stone, custom millwork, and high-end mechanical systems costs significantly more to rebuild than a standard luxury home, and carriers that specialize in this segment, through private client programs, have the underwriting expertise to price that accurately rather than applying generic replacement cost multipliers.
How to Lower High-Value Home Insurance in Florida
Premium reduction on high-value Florida properties is possible, but the most effective strategies require upfront investment rather than simply accepting higher deductibles and hoping for the best.
Update the roof before it reaches the 15-year threshold that triggers surcharges or non-renewal with most carriers. A new roof with hurricane-rated materials and proper installation certification can produce immediate and significant premium reductions.
Add hurricane mitigation features: impact windows and doors, storm shutters, reinforced garage doors, and documented roof-to-wall connections all reduce wind exposure and qualify for Florida’s wind mitigation credits. Getting a certified wind mitigation inspection documents these features formally and can directly reduce the windstorm portion of your premium.
Increase your deductible thoughtfully: raising your non-hurricane deductible reduces premium without dramatically changing your hurricane exposure. The calculation is different for the percentage-based hurricane deductible, where the out-of-pocket implications are larger.
Bundle policies under a private client program: combining home, auto, umbrella, and valuable articles coverage under a single carrier often produces favorable overall pricing and eliminates the coordination gaps between separate carriers.
Install security and monitoring systems: central monitoring, fire suppression, and smart home security features reduce theft and fire exposure and are recognized by most specialist carriers with premium credits.
Compare carriers through an independent advisor: the Florida high-value market varies significantly between carriers, and the same property can receive meaningfully different pricing depending on which carriers are actively writing in your county and what their current risk appetite looks like. Request a comparison through Harbour to see the range of options currently available for your specific property.
Ready to lower your Florida home insurance cost? Request a Florida insurance comparison | Review high value home coverage options
Companies Offering High-Value Home Insurance in Florida
The specialist private client market is the most appropriate segment for $1 million-plus Florida properties, both because of the agreed-value coverage structures and because specialist carriers have maintained more consistent Florida market presence than standard carriers.
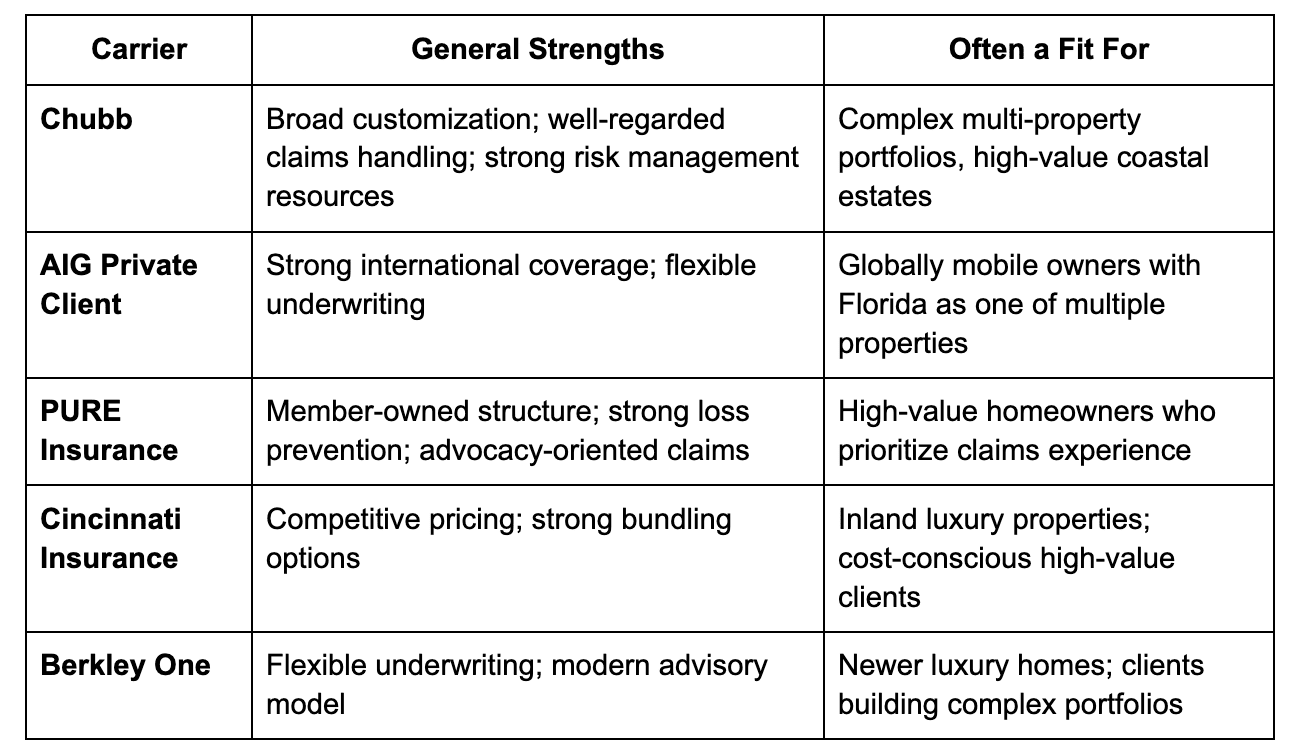
This is not a confirmed list of agency appointments. Harbour Insurance helps clients compare high value home insurance carriers and build customized Florida coverage across the programs that fit their specific property and risk profile.
Contact Harbour to compare high-value Florida home insurance carriers and identify which programs are currently writing in your county.
What Coverage Is Included in High-Value Florida Home Insurance?
A well-structured high-value Florida homeowners policy should include the following coverage components, each of which addresses a specific risk that standard policies either underfund or handle inadequately.
-
Extended replacement cost covers rebuilding beyond the stated dwelling limit if actual construction costs exceed the insured value, which is particularly relevant in post-storm environments where contractor demand and material costs spike.
-
Hurricane coverage with a clearly understood percentage deductible, applied to the insured dwelling value rather than market value. The deductible calculation should be reviewed at every renewal as insured values change.
-
Flood coverage, either through a private flood policy with limits appropriate to the property’s value or through a structured combination of NFIP and excess flood coverage. For most high-value Florida properties, private flood insurance provides more appropriate limits and broader terms.
-
Personal liability coverage with limits that reflect the exposure a high-value Florida property represents, including guest injuries, domestic staff claims, and pool liability.
-
Valuable items coverage for jewelry, art, wine, watches, and other scheduled items that standard homeowners policies handle inadequately. Items need to be scheduled at current appraised value to be covered at current value.
-
Loss of use coverage that funds alternative housing during an extended rebuild after a major loss. For high-value properties, the cost of comparable temporary housing during a 12 to 24-month rebuild can be substantial, and coverage limits should reflect that reality.
What Florida Luxury Homeowners Actually Pay
How much is home insurance in Florida for a luxury property? More than comparable properties elsewhere in the country, and the gap grows as you move toward the coast. But the premium is only part of the picture. The more important question is whether the coverage you’re paying for will actually make you whole after a major loss, and in Florida, that requires getting the structure right: agreed value, appropriate hurricane and flood coverage, and limits that reflect what it actually costs to rebuild what you own.
Compare high value Florida home insurance options to see current pricing for your specific property, or request a luxury property insurance quote from Harbour’s independent advisors who work with the specialist carriers writing high-value Florida risk.
FAQ
How much is home insurance in Florida per month?
Monthly premiums typically range from $250 to $500 for mid-range homes, $500 to $1,500 for properties valued at $1 million to $2 million, and $2,000 or more for luxury coastal properties. Flood coverage adds a separate monthly cost on top of the base homeowners premium.
Why is Florida home insurance so expensive?
The combination of hurricane risk, coastal flood exposure, high rebuilding costs for luxury properties, and a contracted carrier market that has fewer insurers competing for Florida risk all drive premiums above national averages. Coastal properties carry the highest premiums because they face compounded wind and flood exposure.
What is the average homeowners’ insurance cost in Florida?
For high-value properties, annual premiums typically range from $6,000 to $12,000 for $1 million homes and $12,000 to $25,000 for $2 million homes. Coastal location, older roofs, and high-value finishes push premiums toward the upper end of those ranges.
Does Florida require flood insurance?
Florida doesn’t universally require flood insurance, but lenders require it for properties in FEMA-designated high-risk flood zones. For coastal properties, flood coverage is rarely optional in any practical sense, and private flood insurance with higher limits is typically more appropriate than NFIP coverage for high-value properties.
How much is hurricane insurance in Florida?
Hurricane coverage is typically included in the standard homeowners policy but carries a separate percentage-based deductible of 2% to 5% of the insured dwelling value. On a $2 million home, that means $40,000 to $100,000 in out-of-pocket exposure before coverage activates.
Does location affect insurance costs in Florida?
Significantly. Coastal counties in Southeast and Southwest Florida carry the highest premiums in the state. The same home a few miles inland can carry 20% to 40% lower premiums than a comparable waterfront property.
Can I lower home insurance in Florida?
Yes. The most effective strategies are updating the roof before it triggers surcharges, adding certified hurricane mitigation features, bundling policies under a private client program, and comparing carriers through an independent advisor who can identify current market options for your specific property and county.
Which companies offer high-value Florida home insurance?
Specialist private client carriers including Chubb, AIG Private Client, PURE Insurance, Cincinnati Insurance, and Berkley One are the primary options for high-value Florida properties. An independent advisor compares options across carriers based on your specific property profile and location.




